

- You are here:
- Home »
- Blog »
- Invest & Retire »
- A Review of My 2014 Income Tax Results and 2015 Tax Planning
Groups I Am a Part Of



A Review of My 2014 Income Tax Results and 2015 Tax Planning
The past year has been quite a whirlwind. I finished my PhD program in Virginia, got married, went on an awesome honeymoon to Belize (great place to go by the way!), did the post-PhD job search/interview process, moved to Colorado to start the post-PhD job, bought a house in Colorado, and now have our first child on the way (due January 12th, his name is Alex – see picture below!).
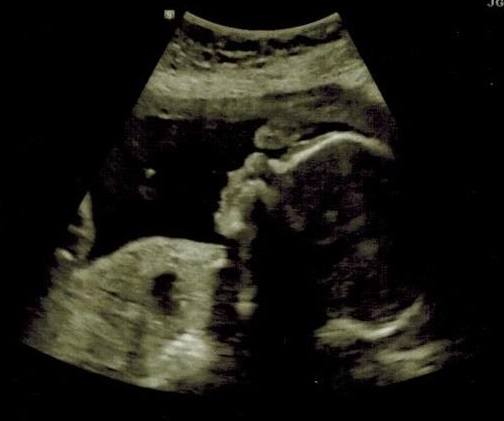
Anyhow, all of that is to say that I am a bit behind on getting this post out. Normally, I do this post in around the April-May time-frame, but better late than never, right?!
In general, the results of filing my wife and my [married filing jointly] 2014 taxes were very good, as I felt like we leveraged the tax code to the best of our ability in order to maximize wealth. As has become my habit over the past few years, I feel that by analyzing some of the finer details/numbers, I can better plan for how to approach my tax planning for the 2015 and beyond year.
2014 Income Breakdown
Our combined total 2014 gross income can be broken down in to the following components:
- 47% from W2-reported wages / income.
- 8% from dividends, capital gains, and interest from investments.
- 25% from untaxed fellowship/wage income for my work as a graduate student.
- 20% from Schedule C self-employed business income.
2014 Deductions
Since the married-filing-jointly standard deduction was greater than our itemized deductions, we took the standard deduction of $12,400 for 2014.
After subtracting the 2 personal exemptions we get for myself and my wife (with no kids, filing jointly), we arrived at a taxable income that was only 68% of our original/total gross income that we started with.
2014 Federal Taxes
Having established our taxable income, our total personal federal taxes were computed. Next, self-employment taxes were added on top of the personal taxes.
This resulted in our total Federal taxes owed for 2014 being ~11% of our overall/total gross income.Nice! I am surprised this percentage is so low!
If we calculate this based on our AGI or taxable income, the percentages become 11% and 16%, respectively.
2014 State Taxes
Since we lived in Virginia January-November and then Colorado during December, we got to pay state taxes in two states for the respective portions of the year.
Our 2014 total state (combined for Virginia and Colorado) taxes owed was calculated to be 4% of my overall/total gross income. If we calculate this based on my federal AGI or federal taxable income, the percentages become 5% and 6%, respectively.
2014 Total (State + Federal) Taxes
If we put everything together from both state and federal taxes, we can find something useful for planning purposes going forward:
- We paid a total tax amount for 2014 equal to 15% of our overall/total gross income.
- Our marginal tax bracket was 15%.
2014 Taxes Owed / Tax Refunds Received
When everything was said and done, we unfortunately had overpaid quite significantly in taxes during the 2014 year. As a result, we received almost a $3,000 in federal tax refund, $800 in a Virginia state tax refund, and we owed $93 for Colorado state tax (since we underpaid slightly).
The primary root cause for the overpayment in federal taxes was paying too much quarterly estimated taxes for my self employment income. This was due to my self employed income dropping in 2014 compared to 2013, and my 2013 taxes owed still being used as the basis for calculating 2014 taxes.
2015 Estimated Taxes – Prospective Planning
One of the nice things that my accountant does do for me each year is to calculate/prepare my estimated taxes for the following tax year (so 2014 was prepared during the 2013 tax preparation round).
Due to our significant overpayment in both state and federal taxes in 2014, our accountant advised us in April 2015 that we did not need to pay quarterly estimated tax payments for our self-employed income for 2015. He did, however, recommend that if we were “having a banner year” and earning much more self employed income than previous years, that I would need to look in to increasing my tax withholding from my post-grad school W2 income.
2015 Estimated Taxes – How It Actually Happened
So, now let’s fast forward 6 months to October 1st, 2015. This is the day I had marked on my calendar to assess our self-employed income and my regular W2 income and tax withholding year-to-date to determine if we were paying enough taxes (since the accountant advised that we didn’t need to send quarterly estimated taxes for 2015).
I proceed to add up my projected W2 income, our combined self-employed income, taxable interest, ordinary dividends, and capital gains. I then subtracted out the deductible part of self employed income taxes, student loan interest deductions, the standard married filing jointly deduction, and our two personal exemptions.
Upon arriving at our approximate taxable income and taxes owed, I was quite surprised to find out that, without changes/intervention, we were en route to be $8-10k behind in federal taxes owed for 2015 (state taxes owed were on track). As this is greater than 10% of our total taxes owed for 2015, an underpayment penalty would apply come April 2016 when we file our 2015 tax return.
Clearly, some drastic changes were needed to correct this. As such, since October, our main focus financially has been to 1) increase the amount of taxes withheld from my regular W2 income and 2) decrease our taxable income to as close as we can possibly get to the 15% marginal tax bracket level.
Specifically, listed below are the actions we took starting in October:
- Dropped the number of exemptions for my W2 income from 2 to 0 to increase the amount of taxes withdrawn from each paycheck.
- Requested that $1,000 additional federal taxes be withheld from each of my biweekly paychecks.
- Contributed as much as possible to regular/pre-tax retirement accounts to reduce our taxable income:
- As we had already maxed out our Roth IRA contributions this year, we could not contribute any additional funds to our regular IRAs.
- We stopped contributing to my job’s Roth 401k and our Vanguard Self Employed Roth 401ks, and instead have been contributing to our regular 401ks.
- $5,250 contributed YTD to my wife’s pre-tax self employed 401k.
- $935 contributed YTD to my job’s pre-tax 401k.
- $1,774 contributed YTD to my pre-tax self employed 401k.
With these drastic actions, my wife and I are now on track with our federal taxes and should not have to pay penalties when we file for 2015.
Plan for 2015 Tax Filing – Accountant or Online Software?
Overall, 2015 has been a year of big changes from a financial perspective, as I went from a graduate school income to having a real job and my wife has been earning more self-employment income the past few months, in spite of becoming increasingly pregnant! 🙂
Because of all these financial changes, it’s understandable that our taxes experienced a bit of a “windfall,” and we are now having to play a little catch-up. However, it sort of makes you wonder – should our accountant who did our 2014 tax return advised us a little better and anticipated these changes? After all, they did advise that estimated tax payment likely wouldn’t be required.
In thinking about it, I don’t blame the accountant for a lack of attention or not doing a complete job. However, at the same time, I am not overly impressed, and it does make me question the value proposition, especially given that the accountant tax prep fee for 2014 was $685, whereas in previous years, I was charged a prep fee of $250.
Given the considerations above and the fact that we have moved from Virginia to Colorado (and we do not yet have an accountant here in Colorado yet), I believe that I will try my hand at using an online tax preparation software for filing our 2015 taxes.
The question then becomes, which online platform should I use?
As I found in my previous detailed explorations of Tax Act, H&R Block, and Turbotax, my favorite online tax preparation platform was Tax Act. As such, I believe I will use Tax Act for filing my 2015 returns.
How about you all? Are you on track with your 2015 taxes? Do you expect to have a tax refund or owe taxes when you file? Will you file using an online tax prep platform or use an accountant?
Share your experiences by commenting below!
About the Author Jacob A Irwin
Hi folks! My name is Jacob. I am the owner and operator of My Personal Finance Journey. I started this blog in January of 2010 and have enjoyed the journey ever since. Since finishing up graduate school in Virginia in 2014, I have been working in biopharmaceutical development in Colorado. You can read more about me and this site here. Please contact me if you have any questions!
Related Posts
Lifetime Income Strategies: Leveraging Annuities for a Comfortable Retirement
Unlocking the Power of Tax Refund Loans: Accelerating Financial Growth with Smart Borrowing
Three Tax Strategies to Consider Before Selling an Investment Property
5 Ways To Start Investing With Less Than $1,000
What Are the Golden Rules for Investing in Gold?
Popular posts
Session expired
Please log in again. The login page will open in a new tab. After logging in you can close it and return to this page.
Having done a few tax years (almost 50!!) I have tried numerous approaches. In your situation, I would suggest your doing your own taxes then finding an accountant and “Buying” a hour of their time to review your work and make any suggestions they see might be helpful. With your doing taxes for the first time in a new situation (Full time employment, in a new state, with extra considerations including self employment and moving expenses – you are looking into using those, right?) having a pro review it looking for missed or miss-calculated items seems to be wise. On several occasions when I was doing that the accountant saved me 10 times their fee or more. Call around, as long as you are doing it in February or early March I would expect you can find someone with time and willing to do it for $100 or less. I found that an accountant in a small or single person office is often more accessible and financially affordable than big accounting firms who charge $300+ per hour to their corporate clients.
Thanks so much for your comment Joe! That’s an intriguing approach to have an accountant review my taxes vs. doing their standard preparation process. I could see that saving some money. What’s the best manner you have found to do that review? Do you set up a meeting face to face, or send them your “draft” return and just have them review on their own time?
I am looking in to self employment expense deductions. However, my new company thankfully paid for all of my moving expenses, so I won’t need to deduct those.
Jacob A Irwin recently posted…4 Reasons A Line Of Credit Is NOT A Good Emergency Fund